Thursday, July 10, 2008

Mobile and travel - my new business

It's been a very long time since I wrote here, and much has changed with me.

I no longer work for a hardware manufacturer flogging transport and mobile backhaul products.

I have an internet startup - www.thetraveleditor.com

It's an online travel guide, targeted at the busy professional who is discerning and demands more from travel.

We use professional travel writers and also travel bloggers to give real expert opinions of hotels, restaurants, bars and attractions. Our audience is middle to upper tier in their taste. Our writers can promote themselves to the community and interact directly with their readership. Each writer's personality is important, and indeed the diversity of our writers adds to the richness of the site.

Our audience is educated individuals, with higher disposable income who appreciate authoritative advice and enjoy the cultural/enriching aspects of travel. They are typically time-starved due to the demands of their work and social life. Accordingly, the articles on TheTravelEditor.com are short, personal and to the point.

We're starting to introduce themed pieces as well - food and drink, yoga retreats, spas, rail journeys, road trips. We also do Top 10s, longer feature pieces and other round ups which add a magazine-y feel to the trip planning content. These are great fun and our writers like to produce these.

So what's this got to do with mobile? Well, read on.

Surprisingly, there is a massive gap in the market for mobile and portable travel content. Don't believe me? Go to Expedia and try to find some.

There is some stuff out there: MP3 walking tours to download to your iPod for example are starting to pop up.

But no one has really exploited the opportunity presented by the fact we all carry smartphones and iPods, the mobile networks are broadband and WiFi is everywhere.

This is a wide open area, especially for travellers. How many times have you walked out of your hotel, and despite what you may have read in the guidebook, you still ask your wife "Where shall we go for dinner?" I do that all the time. This is merely one example of a specific customer problem which could be solved by a mobile solution.

We at TheTravelEditor.com see this as a huge opportunity and are investing our resources in this area. I shall use this blog to update you on our progress and also other mobile developments as they relate to travel.

It's good to be back.

Wednesday, June 13, 2007

Telco 2.0 Mashups - an alternative to IMS?

There’s a fascinating debate currently around how mobile and fixed operators should develop new revenue-generating services. The now traditional view centers around IMS and SIP. But some are now saying that instead operators will have to adapt to the Web 2.0 world, using the concept of "mashups" to quickly create new Web-based services. A recent report from Light Reading delves deep into this idea: Telco Web 2.0 Mashups: A New Blueprint for Service Creation.

Basically, the argument goes something like this:

Should mobile and fixed telcos:

1. Continue on their path of trying to become media and content companies or
2. Move toward a ‘network abstraction’ model where they back away from providing content directly and instead provide APIs which are valuable to 3rd parties (e.g. location API, identity API, micropayments…..).

To be successful at (1) you need economies of scale. You’ve got enormous burdens of content licensing, content management and delivery technology, market research costs, software development, etc. If you want to put this all in IMS, then you’ve got that burden as well. Then add to it the network-level table stakes – cell sites, FTTx, transmission and routing capacity. Only companies like Voda, Orange, ATT et al have a chance of making this model work. But this model clearly implies (in my mind at least) a mass market approach – again, economies of scale are critical. Anyway, telcos by nature are mass market beasts. Operators that don’t successfully insert themselves in the value chain, probably by wielding their sheer mass alone, will be disintermediated. They’ll be forcibly transformed into a utility as their data/internet-hungry customers churn away.

Model (2) requires a bit of enlightened self-interest. Operator realizes that they could not succeed at (1), but rather than be relegated to utility or pipe status they create a position in the value chain for themselves. What can an operator offer Google, MySpace and every dinky web developer out there? Info about the customer that only they have access to – location and identity pop into my head but there could be more. This model reaches the long tail as well and encourages web companies to come to the operator rather than the other way around which is how it is today. This space is wide open at this point in time.

My thoughts on the matter….. I think operators who use IMS to go head to head with web and media companies will lose. The only exception to this could be Voda, Orange, ATT and the like. Due to their sheer size they could entrench themselves in the value chain and refuse to budge. But model (2) is still a long way away. So, in the short/medium term operators should stick with what they are good at - mass market services. During this period they should continue to drive costs out of their businesses which will give them longevity. Also during this period they should work with web companies to develop the tools needed to make model (2) work. I don’t have an opinion on standards based vs proprietary at this point. A well-respected colleague of mine has a more stony view on the situation - he believes that this trend will accelerate telecom operators’ transformation into utilities – no matter how much they fancy themselves to be “content providers”.

Tuesday, April 17, 2007

Forum Oxford - Future Technologies Conference

Forum Oxford's Future Technologies Conference was last Friday 13th April. Unfortunately I wasn't able to attend as I was finishing up a presentation for this year's TNMO in Budapest where I'm speaking.

Focusing on next gen mobile applications, business models and industry issues in general, Forum Oxford is an online 'discussion forum' that has over 1000 members from something like 70 countries. It's free to join and lots of very smart people are members. Check it out.

Thursday, March 29, 2007

"Femto-nomics"

Apologies for the radio silence....it is very easy to fall out of the habit of writing.

Let's talk about Femtocells. These small, low-cost indoor base stations promise substantial cost savings and new service opportunities and are generating intense interest from operators.

The main benefits of Femtocells are:
1. Fixed-Mobile Convergence (FMC): 3G femtocells enable MNOs to offer relatively inexpensive, high quality voice for users when they are at home. Also helps to maintain the "mobile premium" when subs are out and about.
2. Bundles and group subscriptions: to attract all household members to the network.
3. Compete effectively with WLAN/UMA: without the need for dual mode handsets.
4. Cheaper to deploy and manage than macrocells.

Some analysts predict that 3G femtocells have far-reaching consequences for the industry. Operators need to improve in-building coverage significantly, and 3G femtocells offer a practical, and potentially much less expensive, alternative to further investment in 3G macrocell networks. They believe that femtocells in sufficient densities could even make macrocell investment redundant. Note I said in sufficient densities.

Analysys Research claims that "Mobile operators could benefit significantly - particularly if they have a small number of customers. A typical small operator could save an average of about USD45 per customer per year by deploying 3G femtocells in 60% of customer households by 2012."

That's equivalent to adding around 10% to ARPU. Sounds pretty compelling. Let's buy a bunch.

Not so fast....They then go on to say that operators could end up shooting themselves in the foot: "Mobile operators that fail to adopt a large-scale approach may find themselves expending great effort on integrating a large number of 3G femtocells without avoiding significant macrocell investment, if most of their customers do not take up femtocells. 3G femtocell deployment to 20% of households by 2012 would only save about USD20 per customer per year, because significant numbers of macrocells would still be needed."

Sounds like an 'all or nothin' ' situation. No doubt operators will have to subsidize the Femtocells, quite likely footing 100% of the bill. At only USD45 per person savings in the best case, Femtocells won't make sense unless the sub signs up for some bundle or a family subscription. It will help the business case even further if the MNO is also the broadband provider. However, even with all these potential revenue sources, it still seems to me that the operator will have to more or less blanket a region for Femtocells to make economic sense.

Thoughts and comments welcome.

Tuesday, January 16, 2007

3 scraps roaming fees - Viv must be ecstatic

'3' announced today that they're scrapping roaming fees in the 8 countries where they operate 3G networks - Italy, Sweden, Denmark, Austria, Hong Kong, Australia, UK and Ireland. Called '3 Like Home' there are no one-off fees, no connection fees, no incoming call termination fees, nothing. Voice minutes and messages come out of your bundle. And presumably, if you're on X-Series, then your data usage is free.

What a great development - I applaude the guys at '3' for really taking the lead. They took the wrecking ball to the walled garden with X-Series and now they're doing the same with roaming fees. Vivien Reding of the European Commission must be very happy indeed.

I have long ranted about how the mobile industry suppresses the mobile internet and finds any outside (3rd party) innovation incredibly suspicious and even dangerous. Even '3' was like this for the longest time - they were one of the strongest advocates of the walled garden and a restricted mobile experience.

No other operator has moved in response to X-Series.
And now '3' has upped the ante again.

Vodafone, T-Mobile and O2 all cut their roaming fees last summer presumably to delay any meddling by the EC. I guess at the time they were even seen as being 'leaders' - certainly relatively speaking since roaming fees were so extortionate to begin with. But now '3' has one-upped them on roaming as well as data.

I can't wait to see what's going to happen next.

Tuesday, December 12, 2006

I'm speaking at the Light Reading Backhaul Strategies conference

I'm part of the morning panel session talking about low cost IP migration options for mobile backhaul. And I have a speaking slot in the afternoon where I'll talk about 3GPP Rel. 5 transmission issues and how Ethernet can solve them. Here's the event URL.

If you're near the Langham Hotel, then give me a ring or SMS and we can meet for a drink after!

Monday, December 11, 2006

Penetration rates of 250%? Why not?

In my last post, I suggested that multi-mobile subscription bundles, or 'second subscription' as it's becoming known as, could be a lucrative strategy for mobile operators. They lock in the customer and encourage usage through attractive pricing and by getting another phone in their hands.

Until now, I haven't heard of any mobile operators actively addressing this opportunity. But at a recent conference in London, Sunrise (TDC Switzerland) claimed that they are going to actively target the multi-subsription market. As far as I know Sunrise are the first to have a formal strategy for this - anyone out there know of any others?

Sunrise also offers residential broadband, so they can easily create a multi-SIM + broadband package which as I mentioned before would lock in customers pretty tightly. I would love to see the take-up and new churn rates so I hope they can pull it off.

Now, regarding handsets. Multi-SIM handsets don't exist, but if multi-subscription takes off, then there will be a market for them. But not everyone will want a single device - some people, myself included, like to have separate phones. People already have 1-2 mobiles, iPod, digital camera, laptop, Blackberry, etc.... As Dean Bubley recently blogged, "I see people having a selection of devices they could use at any time, and selecting the most appropriate depending on whether they are going out for work/play, have access to power sockets, how many pockets they have in that day's clothes, what applications they think they'll need etc."

Functionality and style have to be relevant to where/when I will have my device and they must be balanced by practical aspects as form factor. I think multi-subscription bundles could create a whole new market for products that are 'context specific.'

The iPhone could be the first.....

Monday, October 16, 2006

Skewed penetration but straightforward strategy

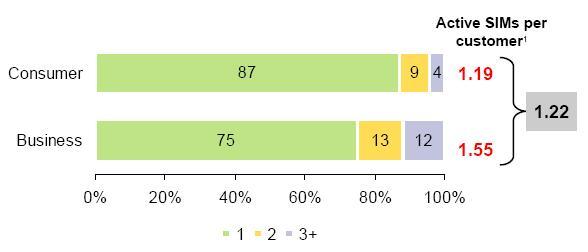
There’s a lot of debate as to how one adjusts mobile penetration rates to properly size the actual market opportunity. But it’s not just about getting phones in the hands of the phone-less. It’s also about converting single SIM subs to dual, dual SIM subs to triple, etc. I have a gut feeling that expanding multi-SIM penetration (do I hear penetration rates of 250%?) could be a real growth area. But I’m not sure operators are actually addressing that particular opportunity.

I saw a Vodafone presentation recently that showed that in the UK, Germany and Spain, consumer subs had an average 1.19 SIMs each and business subs had an amazing 1.55 SIMs each on average. In fact, 12% of the business subs had 3 or more active SIMs. The consolidated figure, for consumer and business subs, was 1.22 SIMs per sub. With that knowledge, it's pretty simple math to work out the actual phone-less population.


Who are these phone-less people? My gran for one. My 2 year old for another. In other words, people who, if they did sign up for a mobile, would have such low ARPU that they'd be cost prohibitive to keep on the books.

So, mobile operators trying to build mobile market share have 2 options: Fight tooth and nail for churners - a pretty tough and expensive fight and does nothing to improve customer loyalty. Or they could target the multi-SIM market and build market share by increasing SIM penetration. I think multi-SIM presents a lucrative opportunity for some creative bundling. Particularly now that mobile operators are jumping into fixed line services.

I'm a multi-SIM guy and like me I think most multi-SIM folks are also multi-operator. So an interesting strategy could be for the operator to be the supplier for all my mobile comms needs: business 1, business 2, personal 1, etc....you get the picture. They’d be increasing the total comms market by getting more SIMs in more peoples’ hands which should lead to increased usage, but more importantly they’re locking me in by bundling multiple accounts at a good price. Mobile number portability is still a pretty painful process, and that’s just when I want to move a single number. If I had to move 2 numbers, I’d probably think twice before going there.

Add to the bundle my home broadband service and my switching costs suddenly skyrocket. I'm pretty much hooked in for life.

Thursday, September 07, 2006

Mobile premium is 4x

I like Sprint. They're always doing stuff which give me things to talk about.

Take their announcement about offering Novatel's Merlin S720 EVDO Rev A data card. This is a nice little device offering up to 850kbps today (presumably over vanilla EVDO) and up to 3.1Mbps when Sprint's Rev A network is switched on.

The interesting bit is that they've valued the mobility premium, which I've blogged about before. For $80/mth for 12 mos. you can get unlimited data usage. Comparing apples to apples here, a similar broadband DSL service would cost under $20 per month. And this is without any bundles. So let's say the mobility premium is 4x to keep the math simple.

Is mobility worth it? Well, clearly this card and tariff is an enterprise offering so a mobility premium of 4X doesn't seem unreasonable. But why doesn't the blasted card support WiFi??? Without WiFi, I think it's completely useless.

Tuesday, August 15, 2006

Sprint's $3bn 4G gamble

I blogged about this before but back then the details were sketchy.

Sprint said on Tuesday it is partnering with Intel, Motorola and Samsung Electronics to build a nationwide mobile WIMAX (802.16e-2005) network and develop devices that will access it. They plan to spend $3bn over the next 2 years, with a launch at the end of 2007. About 100m people will have access to the network by the end of 2008.

Gary Forsee, Sprint's chief executive officer, said the jump to 4G is not a replacement for Sprint's 3G network but will help the company develop a new market for advanced wireless services. Forsee said Sprint envisions a future when a whole slew of new devices - such as music players, video recorders and portable, low-cost PCs - will attach to the wireless network to allow consumers and business users to access content instantaneously over the mobile internet.

Of course he has to say that - his shareholders would crucify him if he admitted that CDMA is a dead-end and any EV-DO investment (upgrade to Rev. A happening this year) was like throwing money down the toilet. Am I being too cynical? Perhaps not. Ditching CDMA has become du jour of late with Telstra being one of the most famous examples. Plus the economics of the situation seem to make WIMAX more attractive than continued CDMA investment. For example:

  1. WIMAX can transmit over greater distances and in a wider spectrum band so the cost of operating will be less than CDMA.
  2. WIMAX chipsets are 1/10th the cost of chips used in EV-DO devices. Sprint's strategy seems to be all about devices, devices, devices. WIMAX is a global standard meaning massive economies of scale for terminals.
  3. Sprint already owns a large portion of the 2.5GHz WIMAX spectrum in the US.
CEO Forsee even admits as much: "The cost performance on the 4G business model and the throughput gains, plus the cost of putting these chips into cameras, gaming devices and other consumer electronics, is what makes it different from EV-DO Revision A."

It just seems strange that their 4G timescales are so aggressive. Why not wait a bit longer and get a better return on EV-DO investment?

Monday, July 03, 2006

Will Mobile TV succeed?

There were 2 interesting reports issued last week by Jupiter and Analysys, both questioning the revenue opportunity of mobile content, and in particular mobile TV.

Jupiter warned that the majority of European subs are unwilling to pay for content and services beyond basic messaging.

Analysys gave similar evidence saying that subs would be unwilling to spend very much on mobile TV.

Mobile TV has been a hot topic for a few months now with everyone and their dog offering their opinion on technology, business models, who owns the value chain, etc etc etc. The jury is still out on how successful it will be and the only thing that is clear is that there are vastly different and contradicting opinions.

Mobile operators and Nokia say it will be a killer app. Others say that TV on the mobile will be niche at best and a money pit at worst.

Boil it all down and the real conundrum, and probably what will make or break mobile TV, is good old fashioned ROI.

DVB-H is supported by the mobile industry. But it requires significant investment in infrastructure, content delivery and billing systems, content acquisition, etc. And then there are handset subsidies to consider. Spectrum is also limited until 2010 in most markets.

DMB is supported by the broadcasting industry because they own DAB spectrum and DMB is very DAB-like. Low infrastructure investment is required. DMB might disintermediate the mobile operators because you don't need a mobile phone to get DMB service. But for market penetration, DMB-enabled mobile phones are required which operators won't subsidize since they're not in the driver's seat in the value chain.

So.....where does this leave us??

If subs don't want to pay for mobile TV, then mobile operators won't want to invest in the infrastucture. Similarly, broadcasters may be reluctant to invest because they won't have the handsets to get critical mass. Arguably
, broadcasters could still make money on lower tariffs (since their up front investment is lower) but they need volume.

Vendors aren't helping matters since they're lining up behind different standards (DVB-H vs DMB being the main battle).

I find it hard to see how mobile TV will succeed unless everyone holds hands and sings kum-ba-ya. A little bit of a large pie is much better than a big bit of a small or nonexistent pie. Economies of scale and willingness to fairly share the value are vital. Unfortunately, the mobile industry is not known for its fondness of ecosystems where they don't make the most money.....

Thursday, June 15, 2006

GSMA-onomics.......

The EC's latest proposal to regulate mobile roaming services by equalising retail prices across the EU will distort a very competitive market, the GSM Association (GSMA) said in a statement today. Here's an article.

According to the GSMA "the Commission plans to impose an arbitrary retail price cap across Europe, ignoring the fundamental geographic, demographic, regulatory and commercial differences between the 25 countries of the European Union."

The GSMA further argues that "the imposition of such a price cap" will reduce competition and innovation among European mobile operators, damaging the industry.

I totally agree with the market distortion points that the GSMA makes. But the fatal flaw in their argument is this notion of a "competitive market."

Yes, competition is fierce within national boundaries. But not across borders.

International roaming can only be described as a cartel.

The spirit of Viviane Reding's proposal is good - she's trying to break the cartel. And only after years of unsuccessful attempts at getting the industry to reduce roaming fees on its own. She really isn't an interventionist.

But, yes, her price cap plan is the wrong way to go about it.

Maybe the threat of intervention is all that is required - look at what Voda, Orange and TMobile did to their roaming rates after Viv's announcement.

3G home gateways - sounds cool to me

There's an interesting idea floating about for putting a "UMTS base-station module into a home gateway connected via ADSL" to provide dedicated 3G access at home. To the consumer, this would appear very much like UMA (e.g. BT's Bluephone), but with some key advantages.

Like UMA, calls made at home would be routed over the broadband connection and would be cheap or free. However with the 3G gateway, there's no need for a dual mode handset (expensive with poor battery life). And, of course, because the consumer is using their standard mobile, this is the device with all of the numbers programmed into it, so there's a huge convenience boost.

Also, quality and breadth of services would improve. Mobile operators could offer lots of different and innovative bundled services.

There're some problems to sort out of course, but they don't seem insurmountable. The most obvious question is whether there is a demand for improved 3G access at home, but apparently so. Indeed research shows that a high proportion of mobile voice calls are made at home - figures of 30% to 40% are often quoted. At the same time, mobile users are generating more and more mobile data traffic while at home.

I know that I use my mobile at home because I can't remember anyone's number any more and I've got a boatload of inclusive minutes that I never seem to use up. Sorry BT.

Thursday, June 08, 2006

U.K. train passengers want WiFi, but won't pay

A very interesting survey was just completed by telecoms consultancy BWCS. Here's an article about it.

Basically it says that there is very clear demand for WiFi connectivity on trains, but price and reliability are keeping usage down.

So what's this mean for a mobile operator wanting to offer a similar WiFi service?

-> Mobile operator wants to offer WiFi service on train to capture lucrative business users and add "bundled value" to consumer users. It could be a wholesale model where train operator offers WiFi for free or for a fee, or it could be a direct MNO to sub relationship. Irrelevant at this point.

-> Problem is users are wanting more bandwidth and greater reliability without paying more (or anything at all). They are also starting to demand symmetric bandwidth which cheap as chips ADSL doesn't do (ADSL is usually used to backhaul WiFi traffic).

-> MNO therefore must find a way of deploying WiFi on trains and collector points along the route (TMobile UK uses WIMAX to collect WiFi traffic on London-Brighton) for next to nothing. Piggy backing on top of the GSM/UMTS transport network seems like a good idea. On the other hand, SDSL backhaul at the WIMAX site is an option but it has all the same issues of backhauling HSDPA over ADSL which I blogged about before.

The best option, if it's available, is a carrier ethernet link. You get your 2G/3G traffic backhauled more or less for free over pseudowires (VLANs), your HSDPA backhauled over a separate VLAN with different QoS, and your WiFi/WIMAX traffic backhauled again over its own VLAN with its own QoS. It's scalable, cheap, high bandwidth and carries both IP and legacy traffic very efficiently.

The skyrocketing demand for high bandwidth, always on data services like WiFi (coffee shops, trains, etc) and eventually HSDPA and WIMAX will drive consolidation in mobile operators' transport networks. And Ethernet will be the backhaul technology of choice.

Thursday, May 18, 2006

ADSL for HSDPA backhaul - bad idea

I am just back from a marathon travel binge - lots of conferences, customer meetings and trips to HQ.

I spent last week in Berlin at Transport Networks for Mobile Operators (TNMO) which is a fantastic show put on by IIR. It is a very well-attended conference focused solely on, you guessed it, transport networks for mobile operators. Backhaul and core network transport.

Most 3G operators are launching HSDPA now or very shortly. This poses a big problem in terms of backhaul capacity since most cell sites have 2 or 3 E1s (4-6Mbps) connecting them to the core, but HSDPA will provide 1.8M or 3.6Mbps to each user (depending on how the operator implements it). You do the math - the current backhaul capacity just won't cut the mustard.

So many operators are adding another E1 and plan on contending the service similar to your residential broadband (20:1, 50:1). That could work for the short term. But the problem is only postponed as you get more and more users (up to 300 per cell) demanding bandwidth and HSDPA evolves to higher bit rates. Simply adding more E1s is too expensive and TDM doesn't transport IP traffic efficiently.

So a lot of operators want to split off HSDPA traffic and backhaul it separately. This makes a lot of sense - keep your best effort data traffic separate from your real-time voice and video. Backhaul for HSDPA doesn't need such stringent QoS as that for voice.

I am a big proponent of using Ethernet for this backhaul (I'll post a separate link as to why I think this is good). But at TNMO a LOT of operators were musing on the benefits of using ADSL: It's cheap, it's all IP, it's ubiquitous and mature, it's asymmetric, etc....but mainly the cost element is what's so attractive.

I think ADSL is a bad idea. Here's why:

1. HSDPA will be contended as I already said. Commercial ADSL services are also contended. QoS will suffer big time.

2. HSDPA will be used for streaming video. DSL providers hate streaming. This is why they all put usage limits on their services.

3. You might say, "Hey, I'll just negotiate an SLA with unlimited usage and zero contention." OK, fine. But how much will that cost? The reason ADSL is cheap in the first place is because of contention and usage limits. It minimises the amount of infrastructure the ISP has to build and operate.

4. OK, say you manage to get a good SLA. Then you start rolling out hundreds of HSDPA sites in high traffic areas (which also happen to be high traffic areas for the ISP. This means capacity bottlenecks for them). I know of NO ISP's network that can cope with the kind of high-capacity streaming traffic that HSDPA will generate.

5. How do you manage hundreds/thousands of DSL modems?

6. It's yet another overlay network. Mobile operators already know the hassle of overlays from their 3G Rel. 99 experience.

The only time it might make sense is if the mobile operator builds its own DSL network. Dry copper is available in many places now. The business case seems to be sound but I am not sure of the technical problems of self-build. What about operators with sister ISP companies? I think they'll run into the same issues I've outlined above.

I am just not convinced that you'll be able to get the SLAs you need for carrier class ADSL with good QoS. And the management of the network will be a nightmare.

Ethernet is the way to go. It's also cheap, it's also high capacity, and it's carrier class (well, it will be soon). And oh, by the way, you can use Ethernet to backhaul ALL of your TDM and ATM traffic too using 802.1p/q VLANs. Sure, ubiquity is an issue, but the fixed line guys are catching up.

Thursday, April 06, 2006

Sprint to offer EVDO/WiFi router

Sprint announced at CTIA Las Vegas that they will introduce an EVDO-WiFi router and a USB EVDO dongle later this year. These products can turn any Sprint EV-DO card connection into an 802.11g local-area network, according to business marketing program manager Larry Sherrard. The press release is here.

I've already blogged about the radio planning issues that this might cause. And Martin Sauter brought to my attention just recently the Linksys router with an EVDO PCMCIA slot. This is the one that Sprint will offer. Kyocera and a few other vendors offer similar devices.

At $60pm for Sprint subs and $80pm for non-subs this appears to be priced for the SME market moreso than residential.

But what about radio planning and backhaul capacity? Sprint aims to have 190 million people covered by EVDO by the end of this year. And full Rev A coverage by end 2007. They're also going to decommission Nextel's iDEN network and increase cell sites by 40%. And then there's something about announcing a 4G "wireless interactive multimedia" technology later this year......

They've got A LOT going on. Can they pull it off while at the same time offering a good broadband service? Any thoughts from the blogosphere?

Wednesday, March 29, 2006

EU Commissioner bans roaming charges

This is a big deal. And potentially a huge opportunity for mobile operators.

Europeans could see a sharp drop in international phone costs in time for their summer holidays next year as a result of planned laws being rushed through by the European Commission.

The EU Telecoms Commissioner, Viviane Reding, has decreed that roaming charges violate the principles of the free transfer of goods and services within the EU. Mobile operators have essentially been "punishing" their subscribers for travelling.

While the MNOs will certainly complain bitterly and challenge the ruling, it appears that this is really going to happen. The European Commission has been arguing with the mobile industry for some time and is fed up that operators haven't done anything on their own to eliminate roaming fees.

But the cloud has a silver lining for sure. There is very clear price elasticity when it comes to making calls abroad. It costs a lot more so people make shorter or no calls at all. So by getting rid of roaming charges, subs will make more phone calls and send more SMSs. In fact SMS substitutes for voice calls for many people while abroad - it's cheaper to keep in touch with people back home via SMS. The demand is there, but the pricing is inefficient to maximising revenue. Basic microeconomics.

Forward thinking mobile operators will take advantage of the ruling by scrapping roaming charges early and using it as a marketing gimick. Tomi Ahonen explains this in more detail.

It really is good news for everyone - the industry and its customers.

Thursday, March 23, 2006

Fixed/Mobile *Network* Convergence should be a big driver for next gen investment

I seem to be reading a lot of reports lately.

Infonetics has released their latest report: Service Provider Plans for Next Gen and Wireless broadband: North America, Europe and Pacific 2006. It's a survey of 18 North American, European and Asia Pacific wireless carriers and gets their views on why they would deploy next gen mobile networks.

67% of respondents said they viewed offering bundled services as a strong driver for investing in next-generation equipment. Infonetics notes that offering triple-play service, with mobile IPTV, will become increasingly important as voice revenues decline.

Operators are looking at a range of mobile broadband technologies for next-generation networks, including WCDMA, WiFi and WiMAX. Unlicensed technologies such as WiFi and WiMAX present opportunities to provide bundled services. 6% of respondents offer bundled VoIP with WiFi; this is expected to grow to 44% by 2007.

So what about fixed/mobile NETWORK convergence? It just doesn't make sense for a mobile operator to jump into the triple-play fray only offering wireless/mobility. Sure, customers may be happy with a mobile phone instead of a fixed, they may be happy with a wireless broadband connection instead of DSL, but what about TV?

Cable operators already offering triple-play can very easily bolt on a mobile service to make quadruple-play. Witness NTL and Virgin.

Mobile operators absolutely need to build next-gen wireless networks so they can grow revenue and regain the "mobility premium" that's disappearing in voice. But I think they're missing a BIG TRICK by restricting themselves to wireless access only.

After all, mobile operators have huge access networks - why don't they leverage them to offer fixed line services??

Wednesday, March 22, 2006

Latest mobile market forecasts

Portio Research just released their latest mobile market forecasts. Here is a quick summary. There are some interesting conclusions. For example, Russia will plateau during 2006-2011 and there's still a lot of steam left in the good ol' US of A:

Worldwide mobile subs end 2005: 2.129 billion
Forecast for 2011: 3.964 billion

Net adds by region by 2011:

  • Asia Pac: 1 billion
  • Africa: 265 million
  • Latin America: 205 million
  • Middle East: 79 million (largely Iran/Iraq)
  • Central, eastern, southern Europe: 79 million
  • North America: 75 million
  • Northern Europe: 30 million
Asia Pac will account for 50% of total subs by 2011.

Rankings by country:
  • 1 and 2: India and China will have just over a billion subs combined.
  • 3, 4 and 5: Brazil, Indonesia and Nigeria (73 million net adds EACH)
  • 6: USA (66 million net adds)
  • 7-10: Pakistan, Mexico, Bangladesh and Iran (182 million net adds between them)
  • Others: Russia (28 million net adds), Japan (14 million net adds)
Surprisingly, Argentina, South Africa, Saudi Arabia and Canada fall lower in the rankings.

Keep in mind that lower subs growth in developing markets doesn't mean the network operators won't be investing in their networks. In fact they will probably be playing catch up for a long while after the onslaught of next couple of years.

Monday, March 20, 2006

More on mobile broadband - HSDPA report

Informa's just released their latest report on HSDPA deployments and I'm glad to see they've singled out tariffs as being pretty important.

MNO's have so far resisted flat-rate tariffs for mobile broadband. But the fixed line broadband market didn't take off until low flat-rates became a reality. True, some operators have increased their fair usage limits but they are still stifling the market with high prices. The funny thing is that they seem to be aware that they're own pricing policies are the cause of low data usage!

Pricing is still between Euro50 and Euro70 per month, for 1-2Gbit usage.

Is this the "mobility premium" I've talked about before? Yes. And no.

What do I mean by 'yes?' That's easy. MNO's will leverage HSDPA's one key advantage over both fixed DSL and Wi-Fi, mobility, to justify premium pricing. In the voice world, this 'mobility premium' has for years allowed mobile operators to get away with vastly higher tariffs than those charged by the fixed line guys. As competition continues to exert downward pressure on prices and to erode this premium, MNOs will look to leverage HSDPA's mobility benefits to establish a new 'mobile premium' for mobile broadband over its fixed counterparts of Wi-Fi and DSL.

What do I mean by 'no?' I think that they're scared of a free for all. Their networks would fall flat on their faces if people started blasting broadband traffic through a 3G network the same as they do on their DSL at home.